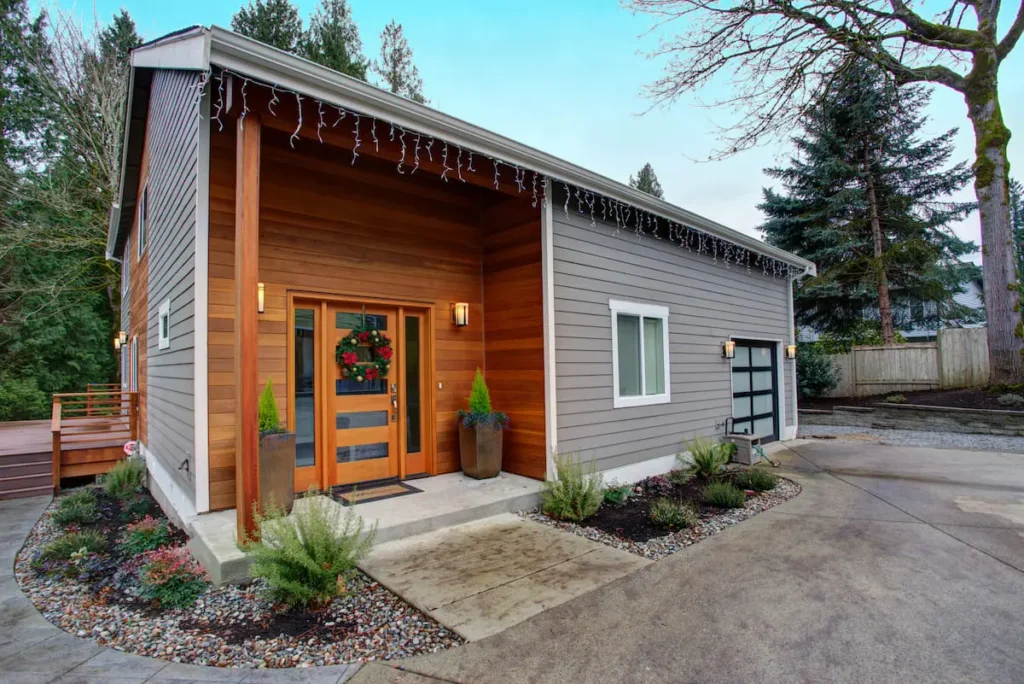
A laneway house or garden suite in Canada can turn unused backyard space into rental income, a home for aging parents, or a place for adult kids to live while they save. Cities including Vancouver, Toronto, Ottawa, and Edmonton now allow detached backyard homes on many residential lots, and British Columbia’s small-scale multi-unit housing rules opened the door wider across the province. But these projects are expensive. In 2026, builders commonly quote $400 to $600 per square foot all-in, and the cheap federal loan many homeowners were counting on never arrived. This guide breaks down real build costs, the financing options that actually exist, and how long rental payback really takes.
Quick Answer
- Cost: Builder estimates for 2026 put a laneway house or garden suite at roughly $400 to $600 per square foot all-in, or about $300,000 to $550,000 for a typical 500 to 900 square foot unit.
- Federal loan: The $80,000 Canada Secondary Suite Loan Program never launched, and Budget 2025 confirmed it will not be implemented. The real federal option is an insured refinance (CMHC, Sagen, or Canada Guaranty) of up to 90% of the as-improved value, under $2 million, approved before construction.
- Payback is slow: At $2,300 to $3,000 a month in rent, simple cash payback on a $400,000 build is roughly 13 to 19 years, before financing costs.
- Best fit: Family housing, long-term property value, or homeowners with lots of equity and low borrowing costs.
What Is the Difference Between a Laneway House and a Garden Suite?
Both are detached, self-contained homes built on the same lot as an existing house. The difference is mainly about access and city rules.
| Type | Where it goes | Typical cities | Typical cost |
|---|---|---|---|
| Laneway house / laneway suite | Back of a lot that faces a public lane | Vancouver (since 2009), Toronto, Victoria and other B.C. cities | $350,000 to $550,000 |
| Garden suite / coach house | Backyard of a lot without a lane; access via side yard | Toronto, Ottawa (“coach houses”), Edmonton, Calgary | $220,000 to $525,000 |
| Secondary suite | Inside the main house, such as a basement apartment | Most Canadian cities | $100,000 to $200,000 |
Vancouver legalized laneway homes in 2009, and a city councillor said in 2025 that more than 6,000 had been built or were under construction. Garden suites rely on side-yard access, which brings fire access rules into play.
Rules on size, height, setbacks, parking, and whether the unit can be sold separately vary by city. In most cities you cannot sever a laneway house and sell it on its own; it stays tied to the main property. Vancouver council directed staff in 2025 to study options for subdividing or stratifying lots with laneway homes, but no change had been made at last check. Several B.C. municipalities and Toronto have also changed rules to allow more units per lot, so check your city’s current zoning before paying a designer.
Can you rent out a laneway house as a short-term rental?
Usually not. Many cities limit short-term rentals to your principal residence, and B.C.’s provincial short-term rental rules restrict them in most larger communities. If you use a CMHC-insured refinance, the suite must not be rented for any period of less than 90 consecutive days, and the private insurers also ban short-term rental use. Plan your numbers around long-term rent.
How Much Does a Laneway House or Garden Suite Cost in 2026?
Costs depend on size, city, site conditions, and finishes. Builder estimates published in 2026 for Vancouver and Toronto cluster in a similar range.
| Project type | Typical size | Estimated all-in cost (2026) | Notes |
|---|---|---|---|
| Basement secondary suite | 500 to 900 sq ft | $100,000 to $200,000 | Uses existing structure; ceiling height and egress are key issues |
| Garden suite (Vancouver) | 400 to 650 sq ft | About $220,000 to $380,000 | Smaller footprint; longer service runs from the street |
| Garden suite (Toronto) | About 600 sq ft | About $365,000 to $525,000 | Roughly $400 to $550 per sq ft |
| Laneway house (Vancouver) | 600 to 1,000 sq ft | About $350,000 to $550,000 | Roughly $400 to $600 per sq ft |
These are builder estimates, not guarantees. Your own quote may land outside them.
What drives the cost up
- Servicing: Running water, sewer, and electrical lines from the street or main house can cost tens of thousands of dollars, especially for garden suites far from the lane. An electrical service upgrade for the main house is a common surprise.
- Design and permits: Architect or designer fees, surveys, arborist reports, permit fees, and development charges where they apply.
- Site work: Tree protection, excavation, poor soil, and slope.
- Materials: Tariffs and trade disputes have pushed some building costs higher. Our article on how counter-tariffs could raise home build and renovation costs explains why lumber, steel, and fixtures can swing your budget.
- GST/HST: Construction costs include GST or HST. Building a new rental unit can also trigger self-supply GST/HST on the value of the new unit in some cases, and rebates may be available, so talk to an accountant before you build.
Build in a contingency of 10% to 15% of the budget. Backyard projects often uncover surprises underground.
Pro Tip: Ask your city for a servicing review before you pay for full drawings. Many garden suite budgets blow up because the water or sewer connection has to run 30 metres or more, or the main house needs a 200-amp electrical upgrade. A one-page feasibility check from your builder or designer, done before design, can save you from paying for plans you can’t afford to build.
Ongoing costs once it is built
Expect higher property tax because your assessed value rises, higher home insurance (tell your insurer about the rental unit), utilities if you include them in rent, maintenance, and periodic vacancies. Rental income is taxable, and you report it on Form T776, where you can deduct expenses and claim capital cost allowance (CCA). Claiming CCA on a unit that is part of your home can affect your principal residence exemption when you sell, so get tax advice first.
How Do You Finance a Laneway House in Canada?
Many homeowners still expect a cheap federal loan for this. That program does not exist. The Canada Secondary Suite Loan Program, announced at up to $80,000 at 2% over 15 years, never became operational, no applications were ever accepted, and Budget 2025 confirmed it will not be implemented. Here are the options that do exist.
Insured refinance for secondary suites (CMHC, Sagen, Canada Guaranty)
Since January 15, 2025, the federal government has allowed insured refinances to help owners add suites, including laneway homes and garden suites. Key terms from CMHC’s product page:
- Up to 90% loan-to-value, based on the lesser of the as-improved value or the as-is value plus the cost of improvements.
- Up to 4 units total, including the existing home, with one unit occupied by you or a close relative.
- Maximum lending or as-improved value below $2,000,000; amortization up to 30 years (a 0.20% premium surcharge applies beyond 25 years).
- At least one borrower or guarantor with a credit score of 600 or higher, and you must qualify at the greater of your contract rate plus 2% or 5.25%, within 39% GDS and 44% TDS.
- Insured financing must be approved before construction starts, or at least at an early stage, and a building permit is needed before the first advance.
- The suite cannot be rented for less than 90 consecutive days.
You apply through a lender, not CMHC directly. Funds are usually released in progress draws as construction milestones are met.
How the premium works. CMHC charges the lesser of a premium on the total loan or a premium on the increase. Owners with plenty of equity pay much less than the headline rates suggest.
| Loan-to-value after refinance | Premium on total loan | Premium on increase |
|---|---|---|
| Up to 65% | 0.60% | 0.60% |
| 65.01% to 75% | 1.70% | 5.90% |
| 75.01% to 80% | 2.40% | 6.05% |
| 80.01% to 85% | 2.80% | 6.20% |
| 85.01% to 90% | 3.10% | 6.25% |
Example: Your home’s as-improved value is $1.7 million, you owe $500,000, and you borrow another $400,000 for the build. Your new loan of $900,000 is about 53% loan-to-value, so the premium is the lesser of 0.60% on $900,000 ($5,400) or 0.60% on the $400,000 increase ($2,400), or $2,400. At 85% to 90% loan-to-value, the cost jumps sharply.
HELOC or conventional refinance
If you have strong equity, a home equity line of credit (HELOC) or a standard refinance up to 80% loan-to-value is often simpler and avoids insurance premiums and the short-term rental restriction. HELOCs are usually priced at prime plus 0.5% to 1%; with prime at 4.45% in October 2026, that is about 4.95% to 5.45%. Interest-only payments keep carrying costs flexible during the build.
Construction mortgages and provincial or city programs
Some lenders offer construction or renovation mortgages with draws. A few cities and provinces have run their own incentives, such as development-charge deferrals, permit fast-tracks, or forgivable loans in return for affordable rents. These change often. B.C., for example, ended its provincial secondary suite incentive program in 2025, so check your municipality’s and province’s housing pages directly.
Steps to take before you commit
- Check zoning and lot fit. Confirm your lot size, lane access, setbacks, and tree rules with your city. Many cities have online eligibility maps.
- Get a feasibility review. A designer or builder can flag servicing and fire-access issues early, before you spend on full drawings.
- Talk to a lender first. Get financing pre-approved, especially for an insured refinance, which must be in place before construction begins.
- Get fixed-price or detailed quotes. Compare at least two or three builders and ask what is excluded.
- Model your cash flow. Use a conservative rent, a vacancy allowance, and a rate at least 1% above today’s to test your budget.
Does a Laneway House Pay for Itself?
Rental payback depends on build cost, rent, and how you finance it. Rents have softened in 2026. Rentals.ca’s September 2026 report showed Vancouver one-bedroom asking rents averaging about $2,380, down 4.8% from a year earlier, and Toronto’s average asking rent across all apartment and condo sizes at about $2,554. A well-built one- or two-bedroom laneway house with a private entrance and yard can rent above those averages, but it is not guaranteed.
A simple payback example
Consider a $400,000 laneway house renting for $2,800 a month:
- Gross rent: $33,600 a year.
- Less vacancy (about 3%), extra property tax, insurance, and maintenance: say $6,000 a year total.
- Net operating income: about $27,600 a year.
- Simple payback with cash: $400,000 ÷ $27,600 ≈ 14.5 years.
| Monthly rent | Net income after $6,000 costs | Simple cash payback on $400,000 |
|---|---|---|
| $2,300 | $21,600 | ~18.5 years |
| $2,800 | $27,600 | ~14.5 years |
| $3,000 | $30,000 | ~13.3 years |
Now add financing. Borrowing the full $400,000 at 5% interest-only costs about $20,000 a year, leaving about $7,600 before income tax. On a 25-year amortization at 5%, payments are about $2,326 a month, or $27,900 a year, so the rent roughly breaks even with the mortgage payment. You build equity over time, but the monthly cash flow is thin.
When it makes the most sense
- Family use: Housing aging parents or adult children can save thousands a year in rent or care costs, value a payback formula misses.
- Long hold periods: If you plan to stay 20+ years, the unit can pay for itself and add to the property’s value.
- Lots of equity, low borrowing: Owners who fund most of the build from savings or a low-rate HELOC see better cash flow.
- Future downsizing: Some owners build the laneway house to live in later and rent out the main house.
It makes less sense if you would stretch your finances to the limit, plan to sell within five years, or count on rent to cover the full mortgage from day one. Keep a cash cushion for vacancies and repairs; our guide on building an emergency fund in Canada can help you size it.
Key Takeaways
- Budget roughly $400 to $600 per square foot all-in in 2026, plus a 10% to 15% contingency.
- The federal $80,000 secondary suite loan never launched; plan around an insured refinance, a HELOC, or a conventional refinance instead.
- Insured refinances can lend up to 90% of the as-improved value under $2 million, but must be approved before you build, and the suite cannot be rented for under 90 consecutive days.
- The premium is the lesser of the rate on the total loan or on the increase, so owners with lots of equity may pay as little as 0.60%.
- On a $400,000 build at $2,800 a month, cash payback is about 14 to 15 years before financing.
- Report rent on Form T776 and get tax advice before claiming CCA, which can affect your principal residence exemption.
- Confirm zoning, servicing, and short-term rental rules with your city before paying for design.
Frequently Asked Questions
How much does it cost to build a laneway house in Canada in 2026?
Most builder estimates fall between about $300,000 and $550,000 for a typical unit, or roughly $400 to $600 per square foot all-in. Servicing, site conditions, and finishes cause the biggest swings. Get several detailed quotes and add a 10% to 15% contingency.
Is the $80,000 secondary suite loan still available?
No. The Canada Secondary Suite Loan Program never became operational, and Budget 2025 confirmed it will not be implemented. The federal option today is an insured refinance through a lender, backed by CMHC, Sagen, or Canada Guaranty.
Can I sell a laneway house separately?
In most Canadian cities, no. A laneway house or garden suite usually cannot be severed and sold on its own, so it stays part of the main property. Vancouver and some other cities are studying changes, so confirm with your municipality.
Do laneway houses increase property value?
They often add value because buyers can use them for rental income or family housing. The increase is usually less than the full build cost, especially in the first few years. Your property assessment and property tax will also rise.
How long does it take to build a laneway house?
Plan for about 12 to 18 months from design to move-in. Design and permits often take 4 to 8 months, and construction usually takes 6 to 10 months. Delays in servicing connections or inspections can add more time.
Can I list my laneway house on Airbnb if I use CMHC financing?
No. CMHC’s secondary suite refinance requires that the suite not be rented for any period shorter than 90 consecutive days, and the private insurers prohibit short-term rentals as well. Many cities and B.C.’s provincial rules also restrict short-term rentals in secondary units.
Conclusion
A laneway house or garden suite in Canada can be a smart long-term move, but in 2026 it is rarely a quick rental win. Build costs of $400 to $600 per square foot and softer rents mean cash payback often takes 13 to 19 years, and longer once you add financing. Skip the cancelled federal loan and compare an insured refinance, a HELOC, and conventional refinancing. Make the decision on family needs, long-term value, and cash flow you can live with. Start by checking your city’s zoning and getting two or three detailed builder quotes.
Get free Canadian money tips every week
TFSA updates, CRA changes, mortgage strategies — straight to your inbox every Thursday. No spam, unsubscribe anytime.
The GetWealthy editorial team writes plain-English guides to Canadian personal finance, based on official CRA, FINTRAC and government sources and reviewed every year.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, tax, or legal advice. Costs, rents, and programs change and vary by city. Always consult a qualified financial advisor, tax professional, or contractor before starting a building project.