Sector Rotation With Canadian ETFs 2026: When Tilting to Energy or Banks Helps
Tilting toward energy when oil climbs or banks when rates settle sounds logical, but a TSX index fund is already about 58% financials and energy.
November and December are when key Canadian deadlines land, from FHSA contributions and donations to tax-loss selling and RESP grants, and when holiday...
A margin account lets you borrow from your brokerage to buy more investments, magnifying gains and losses alike.
A lease almost always has the lower monthly payment, but a loan usually wins if you keep the car. We run the full 2026 math on…
Not buying a home after all? You can move your FHSA savings into your RRSP or RRIF tax-free, without using any RRSP contribution room.
An ESPP match can give you an instant 35% head start on every dollar you contribute, even after tax.
Most stocks, ETFs, bonds and GICs are fine in a TFSA, but holding the wrong asset can trigger a 50% tax on its value.
Eligible Canadian dividends can be taxed at very low, or even negative, marginal rates thanks to the gross-up and dividend tax credit.
Canadian households led by someone 65 or older spent about $53,200 a year on average in 2023. Here's how retirement spending breaks down, how to...
When your term life policy ends, you can renew at a much higher premium, convert to permanent coverage with no medical, or apply for a new…
No employer benefits? Here's what extended health and dental plans cost for self-employed Canadians in 2026, what they cover, how guaranteed-issue...
Breaking a fixed-rate mortgage early can cost five figures, while most variable-rate mortgages charge just three months' interest.
Should you turn part of your RRIF into a life annuity, build a GIC ladder, or keep withdrawing from an invested RRIF?
A three-fund portfolio gives you thousands of stocks and bonds worldwide with just three low-cost Canadian ETFs.
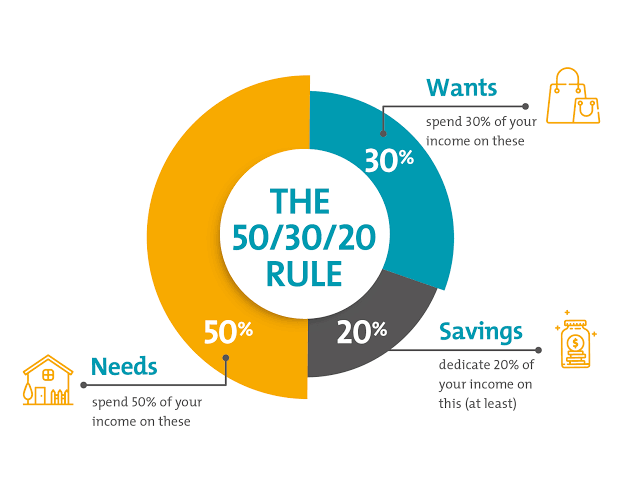
The 50/30/20 rule says needs should take half your take-home pay, but in Toronto or Vancouver, a one-bedroom alone can eat more than that. Here's how…
Real return bonds adjust with inflation, but Ottawa stopped issuing them in 2022, and their prices can still fall sharply.
Splitting a purchase into four "interest-free" payments feels harmless, until late fees, stacked plans, and collections pile up.
Refinancing, selling, or paying off your mortgage early won't get your CMHC premium back. But CMHC's Eco Plus and Eco Improvement programs can refund...
A reverse mortgage lets Canadians 55+ tap home equity with no monthly payments, but at CHIP's posted 7.54% rate the balance can double in about 10…
Gold has nearly tripled in Canadian dollars over five years, then swung wildly in 2026. Here's how the main Canadian gold ETFs compare on fees, how...
Canada has no inheritance tax, but a windfall still needs a plan. Here's a calm, step-by-step 2026 guide: where to park the money, which debts to...
Cash back is simple and guaranteed. Points can be worth more, but only if you redeem them well. We run a real $24,000-a-year household budget through...
With the TSX and S&P 500 both up about 12% in 2026, should you lean toward cheaper value stocks or keep riding growth?
A laneway house or garden suite can add rental income or family housing, but 2026 builds commonly cost $400 to $600 per square foot.
CMHC-insured mortgages need a 600 credit score, but most banks want 680+ for their best rates. Here's what score each lender tier expects in 2026, what...
Swapping Bitcoin for Ether, spending crypto, and earning staking rewards can all trigger tax in Canada, even if you never cash out.
Should you buy the Big Six banks one by one or hold them all through an ETF like ZEB or HEB? We compare 2026 dividends, yields,…
Winter brings fewer buyers and more motivated sellers. CREA data shows January 2026 averaged $652,941 versus $695,412 in April.
Canada has no gift tax, and attribution rules generally don't apply to cash gifts to children 18 or older — so money you give an adult…
Compare no-fee kids and youth bank accounts in Canada, how interest on a child's savings is taxed, and when an RESP or TFSA makes more sense.
Page 2 of 14 — 396 guides total